See the whole plan before you fly it.
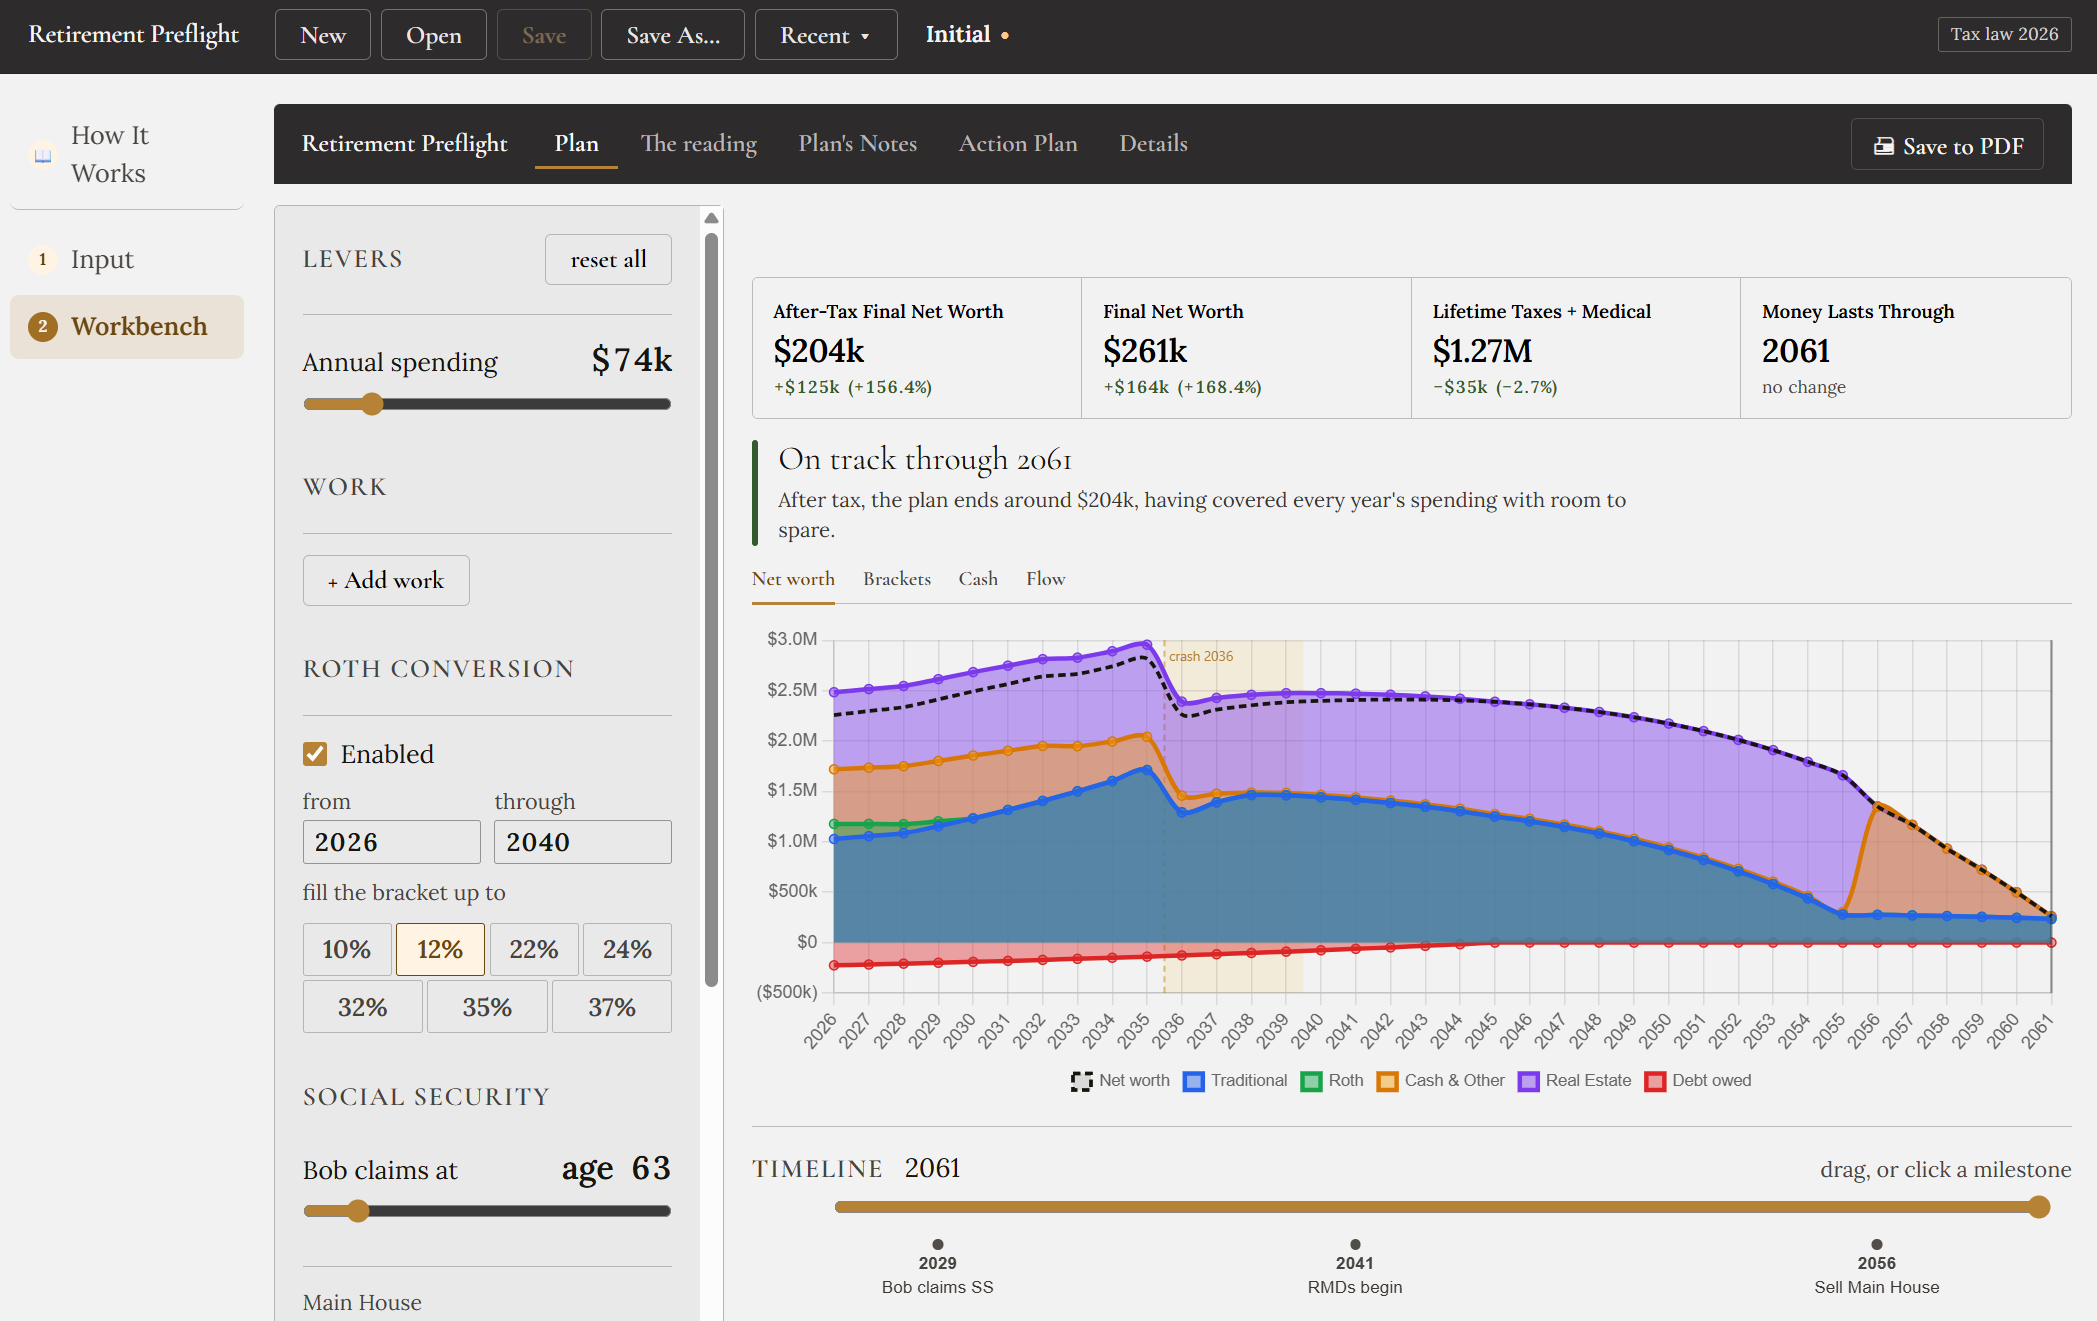
Retirement Preflight is a desktop planner that projects your retirement one year at a time — the tax code included. Federal brackets, all 51 state jurisdictions, Social Security timing, Roth conversions, IRMAA surcharges, ACA subsidies and RMDs, each computed in the order the law actually applies them.
Built for United States tax law, and only for it. Every rule in the engine is a US rule — federal brackets, the 51 state and DC jurisdictions, Social Security, Medicare IRMAA, ACA subsidies, RMDs. It does not model the tax or retirement system of any other country. It is not intended to be sold or used outside the United States, and it produces meaningful results only for a household filing US taxes.
The questions
You have questions about retirement, whether it is still ahead of you or already under way
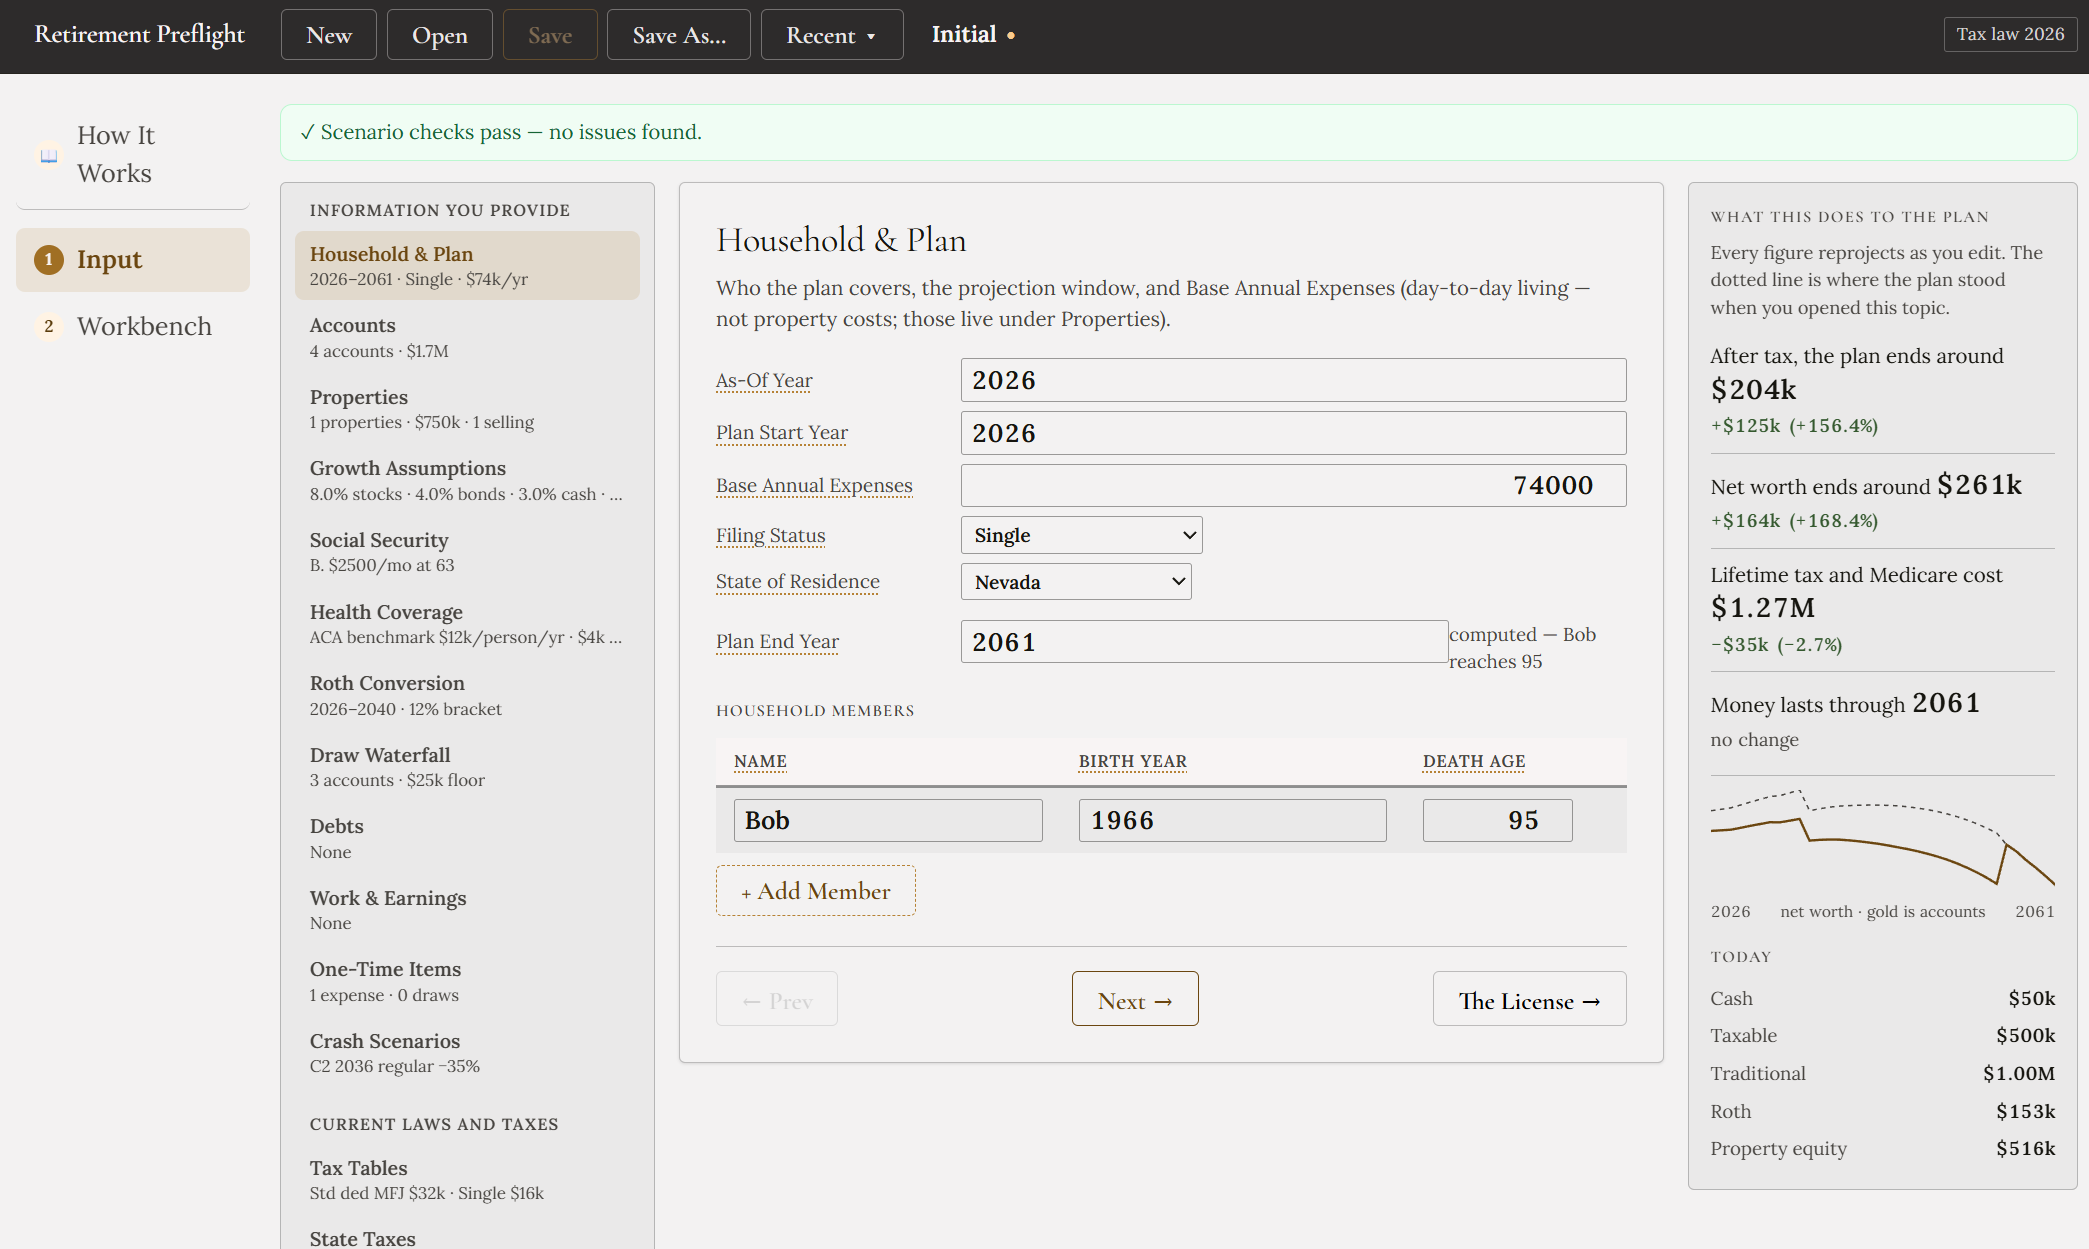
Can I retire now? Should I be doing Roth conversions? Retirement Preflight does not answer those for you. It works out the projection they turn on — year by year, from your own figures and your own assumptions, with the arithmetic in view — so that the answer you come to is yours, and you can see exactly what it rests on.
Those answers depend on each other, which is what makes them so hard to look up. The tax you pay depends on when you claim Social Security. Your Medicare premium depends on your income two years earlier. A conversion that looks cheap this year can cost you an ACA subsidy the next. So the engine works through federal and state tax, healthcare, Social Security, conversions and withdrawals together, one year at a time, starting from your own figures and your own assumptions.
It is not a substitute for a knowledgeable financial adviser, and it does not cover every personal circumstance. What it gives you is a projection you can interrogate: change an assumption, and watch which answers move.
What it models
The parts of a retirement plan that interact
Most calculators apply an average tax rate to a lump sum. The interesting problems live in the interactions — a Roth conversion that lifts your MAGI into the next IRMAA tier two years later, or a withdrawal that crosses the ACA subsidy cliff. Those are the ones this models explicitly.
Federal and all 51 jurisdictions
US federal brackets, the standard deduction, capital gains and NIIT, QBI, the self-employed health-insurance deduction, and every state's own rules — retirement-income exclusions, age deductions, federal-tax deductions and exemption phase-outs included.
Claim timing, done properly
Claim year and month per person, the earnings test if you work while claiming early — and the restoration at Full Retirement Age that most tools forget, which otherwise understates lifetime benefits.
IRMAA and the subsidy cliff
IRMAA surcharges on the two-year MAGI lookback, and ACA premiums on the statutory sliding scale rather than a flat guess — so you can see exactly where the cliff sits relative to your income.
A draw order that knows about tax
Set the account waterfall yourself, or let it look ahead for the 0% long-term capital-gains band — a yearly allowance most strict drain orders never reach.
Market crashes, two at once
Model a downturn and its recovery as one shape, not a drop with a flat rebound. Run two independent crash scenarios over the same plan.
Find Best
Hold your finances fixed and search the decision space — conversion policy, claim timing, sale years — scored against goals you weight yourself. Runs in parallel across your CPU cores.
Privacy
Your financial data never leaves your machine
This is a desktop application, not a web service. There is no account to create, nothing to sign in to, and no server that holds your balances. Your plans are ordinary files on your own disk that you open and save like any other document.
The projection engine is deterministic and runs entirely locally: the same inputs always produce the same output, on your hardware. Your plan and balances never leave the machine. There is no activation server and the app never phones home — your license is checked on your own machine, offline, so the app keeps working with the network unplugged. The only thing it ever asks the internet is whether a newer version exists. Details in the privacy policy.
Pricing
Buy it once
No subscription, ever. The whole application is free to use — every input, the full engine, every what-if, the optimizer, and saving your work. What a license buys is the ability to open a plan again.
| Free | Licensed | |
|---|---|---|
| Every input and the full projection engine | Yes | Yes |
| Workbench: levers, charts, tables, all pages | Yes | Yes |
| Find Best optimizer | Yes | Yes |
| Save and Save As | Yes | Yes |
| PDF reports | Yes, watermarked | Yes |
| Open a saved plan, Recent, double-click a file | — | Yes |
The honest shape of the limit. The free tier is not a trial and does not expire. You can build your whole household, run the optimizer, print the result and save the file — but the free app will not re-open a plan, so each session starts fresh. Save early and save often — the file is written to your own disk either way, and nothing you have typed is lost when you save. We would rather say this plainly here than let you find it at the wrong moment.
Why it costs anything
Almost everything here is given away, and that is deliberate — a planner you cannot fully try is a planner you cannot judge. But two things have to be paid for by something.
The first is the work already in it: a year-by-year engine that applies federal brackets, all 51 state and DC jurisdictions, Social Security timing and its earnings test, IRMAA on its two-year lookback, ACA subsidies on the statutory sliding scale, RMDs and the rest in the order the law actually applies them — and which is checked against an independent tax model rather than asserted to be right.
The second is that none of it stays correct on its own. Every year brackets and the standard deduction are re-indexed, IRMAA tiers and the poverty guidelines are reissued, states amend their own rules, and sometimes Congress changes the rules rather than the numbers. Keeping that current, verifying it, and shipping it as a tested build on two platforms is ongoing work.
A version for each tax year
A subscription would be the easy way to fund that, and we do not want one: an offline tool that stops working because a card expired is a bad deal for somebody who bought a planner precisely so it would still be there. So the shape is the older one instead. Each tax year is its own version of the app, named for the year it carries, bought once and yours forever.
Nothing expires and nothing is taken away. The version you bought keeps running, keeps opening your files, and keeps getting fixes within its own line. When a new tax year is published it arrives as a new version, and whether that is worth buying is a decision you get to make each year rather than one that renews itself. If a year's changes do not affect your plan, skip it — the app tells you which tax year it is running on rather than hiding it, so you can judge.
Between versions the engine does not stop: it grows the most recent published figures forward at your own inflation assumptions and labels every result as extrapolated, rather than presenting a guess as though it were enacted law.
Status
In testing with early users
Version 2026.1.0 is out to beta testers on Windows and macOS. It is not a general release yet: this round is about finding what is unclear or wrong before it ships to everyone.
If you would like to help, the builds are on the downloads page. Testers who commit to using it and sending us a short report about the experience get a free license key; the page explains how to ask for one.
Not financial, tax, investment or legal advice. Retirement Preflight is a calculation and modeling tool. It projects outcomes from assumptions that you choose, and those assumptions — investment returns, inflation, how long you live, what future tax law does — are uncertain and will not match reality exactly. Its output is an illustration, not a prediction, a recommendation, or a plan prepared for your circumstances.
Preflight Retirement LLC is not a registered investment adviser, tax adviser, accountant or law firm, and nothing this software produces creates a professional relationship of any kind. Tax law is intricate and changes; the software may contain errors or model rules in a simplified way. Consult a qualified professional who can look at your actual situation before acting on anything you see here.
United States only. The software models United States federal and state tax law and US retirement and health programs. It does not model the tax, pension, or healthcare system of any other country, and no result it produces should be relied on for a household taxed outside the United States. It is not intended for sale or use outside the United States.